Where to mail 83b election paperwork: file your signed Section 83(b) election with the Internal Revenue Service office where you file your federal income tax return—the same campus as a paper Form 1040 without a payment. As of 29 August 2026, that means Ogden, Utah (84201-0002), Kansas City, Missouri (64999-0002), or Austin, Texas (73301-0002) for most U.S. residents, and often Austin (73301-0215) when you file from abroad with Form 2555 or similar international characteristics. Use IRS Form 15620 (April 2025 revision) or equivalent language that satisfies Treasury Regulation §1.83-2(e), seal the signed original, and document delivery with USPS Certified Mail.
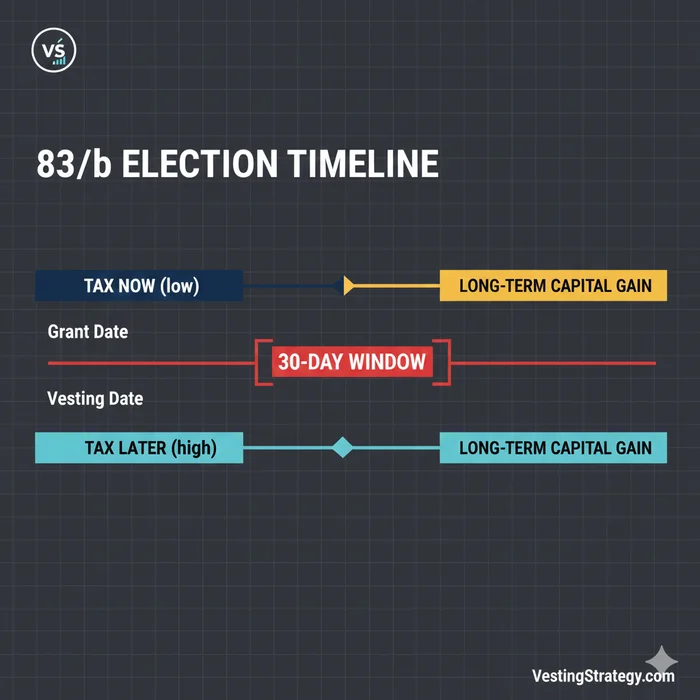
30calendar days to file under Treas. Reg. §1.83-2(b) from property transferVerified against 26 CFR §1.83-2 and IRS Form 15620 instructions (April 2025), accessed 29 August 2026.
The election … is made by filing one copy of a written statement with the internal revenue office with which the person who performed the services files his return.
Pair this directory with deadline math in 83(b) deadline & mailing tracker, online filing in how to file Form 15620 online, and expat strategy in Section 83(b) for expats.
Treasury Regulation §1.83-2: the mailing rule in plain English
Section 83(b) election is an irrevocable choice (once valid) to include restricted property in gross income at transfer instead of at vesting. Treasury Regulation §1.83-2 governs timing, manner, content, and copies—not Form 15620 itself, which the IRS added decades later as a convenience format.
| Regulation paragraph | What it requires | Form 15620 hook |
|---|---|---|
| §1.83-2(b) | File within 30 days of transfer | Box 3 (transfer date); Box 4 (taxable year) |
| §1.83-2(c) | File with IRS office where you file your return | “Where to File” instructions on Form 15620 |
| §1.83-2(d) | Furnish copies to service recipient and transferee | Not a mailing address—but mandatory alongside IRS filing |
| §1.83-2(e)(1)–(7) | Seven content elements in a signed statement | Boxes 1–9 on Form 15620 |
What does Treasury Regulation 1.83-2 say about where to mail an 83(b) election?
Paragraph (c) requires filing with the internal revenue office with which the person who performed the services files their federal income tax return. IRS Form 15620 instructions (April 2025) interpret this as the same address where you mail paper Form 1040 for the active tax year—typically the no-payment row on IRS.gov Where To File tables.
Do not reuse stale ZIP codes. Austin
73301-0002(domestic South) and Austin73301-0215(international) are different destinations. Clerky, Carta, and law-firm templates from 2019 are a common failure mode.
Form 15620 field mapping to §1.83-2(e)
Methodology: On 29 August 2026, we cross-walked each Form 15620 box (April 2025 PDF) against the seven mandatory content items in Treas. Reg. §1.83-2(e). The form is a structured implementation of the regulation—not an optional shortcut.
| Form 15620 field | §1.83-2(e) element | What to enter | Common error |
|---|---|---|---|
| Box 1 — Name, TIN, address | (e)(1) Taxpayer identification | Legal name matching W-2 / cap table | Nickname vs legal entity |
| Box 2 — Property description | (e)(2) Description of property | Class, quantity, issuer legal name | Wrong share class |
| Box 3 — Date transferred | (e)(3) Transfer date | Section 83 transfer date | Exercise click date |
| Box 4 — Taxable year | (e)(3) Taxable year | Calendar year containing Box 3 | Wrong year for late-December transfers |
| Box 5 — Restrictions | (e)(4) Nature of restrictions | Vesting, repurchase, forfeiture narrative | Copy-paste from wrong grant |
| Box 6 — FMV at transfer | (e)(5) FMV without regard to restrictions | Per-share 409A FMV × shares | Using strike price instead of 409A |
| Box 7 — Amount paid | (e)(6) Amount paid for property | Exercise/purchase price aggregate | Forgetting par value paid |
| Box 8 — Income elected | Arithmetic | Box 6 minus Box 7 | Rounding drift |
| Box 9 — Service recipient | Employer copy routing | Employer legal name | Parent vs subsidiary mismatch |
{
  "@context": "https://schema.org",
  "@type": "Dataset",
  "name": "IRS Form 15620 to Treas. Reg. §1.83-2(e) field mapping — Section 83(b) elections",
  "description": "Box-by-box crosswalk of IRS Form 15620 (April 2025) to the seven mandatory content elements in 26 CFR §1.83-2(e), compiled August 2026.",
  "creator": { "@type": "Organization", "name": "VestingStrategy.com Research" },
  "datePublished": "2026-08-29",
  "license": "https://creativecommons.org/licenses/by/4.0/",
  "isAccessibleForFree": true,
  "url": "https://www.vestingstrategy.com/guides/where-to-mail-83b-election/#dataset-form-15620-83b-mapping",
  "distribution": [
    {
      "@type": "DataDownload",
      "encodingFormat": "text/html",
      "contentUrl": "https://www.vestingstrategy.com/guides/where-to-mail-83b-election/#dataset-form-15620-83b-mapping"
    }
  ]
}
Where I'm less sure—whether IRS mailroom staff reject elections that use a regulation-compliant statement without Form 15620 formatting. Anecdotally, practitioners still file plain-language statements when cap-table complexity does not fit the boxes; the §1.83-2(e) content matters more than the PDF template.
Original research: all 50 states → IRS campus (2025 Form 1040, no payment)
Methodology: On 29 August 2026, we parsed the IRS “Where to file paper tax returns” HTML tables for calendar year 2025 individual Form 1040 returns without an enclosed payment, for all 50 states plus the District of Columbia. We normalized each state to one of three campuses and the ZIP+4 suffix -0002 used for routine 1040 filings. Re-verify on IRS.gov the week you mail—campus assignments can change between tax years.
Campus A — Ogden, Utah (84201-0002)
| Mail to | |
|---|---|
| Lines 1–2 | Department of the Treasury |
| Internal Revenue Service | |
| City / ZIP | Ogden, UT 84201-0002 |
States routed here (17): Alaska, California, Colorado, Hawaii, Idaho, Kansas, Michigan, Montana, Nebraska, Nevada, North Dakota, Ohio, Oregon, South Dakota, Utah, Washington, Wyoming.
Campus B — Kansas City, Missouri (64999-0002)
| Mail to | |
|---|---|
| Lines 1–2 | Department of the Treasury |
| Internal Revenue Service | |
| City / ZIP | Kansas City, MO 64999-0002 |
States routed here (21): Connecticut, Delaware, District of Columbia, Illinois, Indiana, Iowa, Kentucky, Maine, Maryland, Massachusetts, Minnesota, Missouri, New Hampshire, New Jersey, New York, Pennsylvania, Rhode Island, Vermont, Virginia, West Virginia, Wisconsin.
Campus C — Austin, Texas (73301-0002)
| Mail to | |
|---|---|
| Lines 1–2 | Department of the Treasury |
| Internal Revenue Service | |
| City / ZIP | Austin, TX 73301-0002 |
States routed here (13): Alabama, Arizona, Arkansas, Florida, Georgia, Louisiana, Mississippi, New Mexico, North Carolina, Oklahoma, South Carolina, Tennessee, Texas.
State-by-state lookup (copy your row)
| State / territory | Campus | ZIP+4 (1040, no payment) |
|---|---|---|
| Alabama | Austin, TX | 73301-0002 |
| Alaska | Ogden, UT | 84201-0002 |
| Arizona | Austin, TX | 73301-0002 |
| Arkansas | Austin, TX | 73301-0002 |
| California | Ogden, UT | 84201-0002 |
| Colorado | Ogden, UT | 84201-0002 |
| Connecticut | Kansas City, MO | 64999-0002 |
| Delaware | Kansas City, MO | 64999-0002 |
| District of Columbia | Kansas City, MO | 64999-0002 |
| Florida | Austin, TX | 73301-0002 |
| Georgia | Austin, TX | 73301-0002 |
| Hawaii | Ogden, UT | 84201-0002 |
| Idaho | Ogden, UT | 84201-0002 |
| Illinois | Kansas City, MO | 64999-0002 |
| Indiana | Kansas City, MO | 64999-0002 |
| Iowa | Kansas City, MO | 64999-0002 |
| Kansas | Ogden, UT | 84201-0002 |
| Kentucky | Kansas City, MO | 64999-0002 |
| Louisiana | Austin, TX | 73301-0002 |
| Maine | Kansas City, MO | 64999-0002 |
| Maryland | Kansas City, MO | 64999-0002 |
| Massachusetts | Kansas City, MO | 64999-0002 |
| Michigan | Ogden, UT | 84201-0002 |
| Minnesota | Kansas City, MO | 64999-0002 |
| Mississippi | Austin, TX | 73301-0002 |
| Missouri | Kansas City, MO | 64999-0002 |
| Montana | Ogden, UT | 84201-0002 |
| Nebraska | Ogden, UT | 84201-0002 |
| Nevada | Ogden, UT | 84201-0002 |
| New Hampshire | Kansas City, MO | 64999-0002 |
| New Jersey | Kansas City, MO | 64999-0002 |
| New Mexico | Austin, TX | 73301-0002 |
| New York | Kansas City, MO | 64999-0002 |
| North Carolina | Austin, TX | 73301-0002 |
| North Dakota | Ogden, UT | 84201-0002 |
| Ohio | Ogden, UT | 84201-0002 |
| Oklahoma | Austin, TX | 73301-0002 |
| Oregon | Ogden, UT | 84201-0002 |
| Pennsylvania | Kansas City, MO | 64999-0002 |
| Rhode Island | Kansas City, MO | 64999-0002 |
| South Carolina | Austin, TX | 73301-0002 |
| South Dakota | Ogden, UT | 84201-0002 |
| Tennessee | Austin, TX | 73301-0002 |
| Texas | Austin, TX | 73301-0002 |
| Utah | Ogden, UT | 84201-0002 |
| Vermont | Kansas City, MO | 64999-0002 |
| Virginia | Kansas City, MO | 64999-0002 |
| Washington | Ogden, UT | 84201-0002 |
| West Virginia | Kansas City, MO | 64999-0002 |
| Wisconsin | Kansas City, MO | 64999-0002 |
| Wyoming | Ogden, UT | 84201-0002 |
Source: IRS Where To File — individual Form 1040, no payment enclosed, calendar year 2025 tables.
What is the IRS 83(b) election mailing address for California?
For California residents filing a paper Form 1040 without a payment under the calendar year 2025 IRS tables, mail the Section 83(b) election to: Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0002. Add an attention line such as Section 83(b) Election — [Your name]. Verify the row for your state on IRS.gov before mailing.
International & expat mailing (non-U.S. addresses)
If you live outside the United States, use an APO/FPO address, file Form 2555 (Foreign Earned Income), or otherwise match the IRS international Form 1040 characteristics, the calendar year 2025 international table directs Form 1040 without a payment to:
| Line | Address |
|---|---|
| Recipient | Department of the Treasury |
| Internal Revenue Service | |
| City / ZIP | Austin, TX 73301-0215 USA |
That 0215 suffix is not interchangeable with domestic Austin 73301-0002. Where I'm less sure—dual-status years, ITIN-only filers who have never filed a U.S. return, and green-card holders who recently moved abroad may need a preparer to choose between international Austin and a former U.S. state campus; a one-page cover letter beats guessing.
Where do expats mail an 83(b) election?
Many U.S. taxpayers abroad filing Form 1040 with international characteristics mail to Department of the Treasury, Internal Revenue Service, Austin, TX 73301-0215 USA when not enclosing a payment—per the IRS international Where To File table. Include a cover letter if your TIN is pending, furnish the employer copy separately, and use trackable USPS international mail or an IRS-designated private delivery service with professional guidance.
Envelope template and §1.83-2(d) copy package
Treas. Reg. §1.83-2(d) requires copies to the service recipient (employer) and, when different, the transferee. Mailing to the IRS satisfies only paragraph (c)—not the employer copy.
| Line | What to write |
|---|---|
| Your return address | Required for Certified Mail; match Form 15620 Box 1 |
| Attention | Section 83(b) Election — [Legal name] |
| Recipient | Department of the Treasury |
| Internal Revenue Service | |
| City, state, ZIP+4 | Campus from tables above |
| Contents | Signed original election + optional one-page cover sheet |
[Your name — return address]
[Street]
[City, State ZIP]

Department of the Treasury
Internal Revenue Service
Ogden, UT 84201-0002

ATTN: Section 83(b) Election — Jane Doe
Replace Ogden with your campus. Anecdotally, IRS mailrooms route faster when the attention line states Section 83(b)—I haven't tested delivery times across campuses with controlled trials.
| Package item | Regulation hook | Destination |
|---|---|---|
| Signed original | §1.83-2(c) | IRS campus (this guide) |
| Duplicate signed copy | Return attachment | Your CPA / Form 1040 file |
| Employer copy | §1.83-2(d) | Stock Administration portal |
| 409A / board FMV backup | Audit defense | Your permanent tax folder |
Certified mail checklist (execution, not theory)
Certified Mail is not required by §1.83-2, but it is the default proof package because IRC §7502 can treat certain timely U.S. Postal Service postmarks as timely filing even when IRS processing arrives later—facts get litigated near day 30.1
Filing proof methods for Section 83(b) elections
Compared for a U.S. employee mailing a paper election near the statutory deadline (May 2026 practitioner norms).
| Attribute | USPS Certified Mail | USPS Priority Mail | Hand delivery to campus |
|---|---|---|---|
| Third-party acceptance timestamp | Strong (PS Form 3800) | Tracking only | Varies—get stamped receipt if available |
| IRC §7502 postmark analysis | Commonly relied on | Validate with counsel | Different rules |
| Cost (approx.) | ~$4–$8 + postage | ~$10–$20 | Travel cost |
| Our default recommendation | Yes for most employees | Only with CPA sign-off near deadline | Rare |
Working checklist — post office
Mail vs. e-file Form 15620 (August 2026)
Recommended: IRS online Form 15620
| Feature | USPS Certified Mail | IRS online Form 15620 |
|---|---|---|
| Treas. Reg. §1.83-2 compliance | Satisfies (c) when timely and complete | Satisfies (c) via electronic filing |
| Proof package | PS Form 3800 + tracking PDF | IRS confirmation PDF same day |
| Setup time | Same day at post office | ID.me may take 24–48h first time |
| Our default? | Day 20+ or ID.me not ready | Day 1–15 when ID.me is set up |
Critical Warning: Certified Mail proves USPS acceptance—not automatic IRS receipt. File by day 25 when possible; see official 30-day deadline & mailing rules.
Worked example: Marco, founder in Lisbon (U.S. citizen abroad)
Facts (hypothetical): Marco, a U.S. citizen, early-exercised 12,000 unvested shares of Northwind Analytics, Inc. on 10 May 2026 while living in Lisbon. He files Form 2555 on a calendar-year basis and has historically used the international Form 1040 mailing table.
| Step | Action | Address / proof |
|---|---|---|
| 1 | Confirm Section 83 transfer date with Stock Admin | 10 May 2026 |
| 2 | Sign Form 15620; TIN field shows SSN | Cover letter notes U.S. citizen abroad |
| 3 | Mail original via USPS trackable service | Austin, TX 73301-0215 USA |
| 4 | Upload employer copy to equity portal | Screenshot with timestamp |
| 5 | Archive Certified Mail receipt + tracking PDF | Permanent tax folder |
Verdict for Marco: Use international Austin 0215, not domestic 0002, and escalate to counsel if his preparer says he is still a state resident filing domestic 1040—address choice follows return filing location, not where he exercises.
Worked example: Jenna, restricted stock in Brooklyn
Facts (hypothetical): Jenna, a product lead at a NYC fintech, receives 8,000 restricted shares on 1 June 2026. She is a New York resident filing paper Form 1040 without payment.
| Item | Value |
|---|---|
| IRS campus | Kansas City, MO |
| ZIP+4 | 64999-0002 |
| 30th calendar day | 1 July 2026 (confirm §7503 if weekend/holiday) |
| Mail-by target | 26 June 2026 (buffer) |
| Proof | USPS Certified Mail, PS Form 3800 |
Jenna should not mail to Ogden because a California colleague did—New York rows point to Kansas City under the 2025 tables.
Steel-man: “FedEx overnight to Austin is safer than Certified Mail”
Best case for overnight courier: You are two business days from the deadline, international postal service is unreliable, or you want signature tracking from a private delivery service (PDS) on the IRS designated list. FedEx and UPS can deliver to IRS campuses with documented chain of custody.
Where couriers disappoint: IRC §7502 postmark rules for U.S. Postal Service mail differ from PDS timeliness tests under Treas. Reg. §301.7502-1. Paying $45+ for overnight (FedEx retail rates checked 14 May 2026) does not cure a missed substantive 30-day transfer window under §1.83-2(b), and mis-addressing 73301-0002 vs 73301-0215 still wastes the spend.
Our position: For domestic employees with 5+ days left, USPS Certified Mail to the correct campus is the right default. Use PDS only with preparer-written instructions—and never substitute courier tracking for confirming the transfer date with Stock Administration.
Common address mistakes (and fixes)
| Mistake | Why it hurts | Fix |
|---|---|---|
| Using employer HQ state instead of your residence | Wrong campus | Use your Form 1040 filing address |
Domestic Austin 73301-0002 while filing international 1040 | Mis-delivery risk | Use 73301-0215 when international table applies |
| Mailing only to IRS, skipping employer copy | §1.83-2(d) gap | Furnish copies to service recipient |
| Enclosing a tax payment in the election envelope | Wrong payment address row | Use no payment row unless CPA instructs otherwise |
| Trusting a 2018 blog “single Austin address” | ZIP drift | Re-open IRS.gov tables |
Related guides
| Need | Article |
|---|---|
| Step-by-step filing playbook | How to file a Section 83(b): step-by-step |
| Form 15620 + official filing bundle | How to file an official Section 83(b) |
| Form 15620 online (ID.me) | How to file Form 15620 online |
| All-in-one address + deadline + generator | IRS Section 83(b) mailing address & checklist |
| Deadline math + mail-by buffer | 83(b) deadline & mailing tracker |
| Postmarks & IRC §7502 | Official 30-day deadline & mailing rules |
Verdict
For the query where to mail 83b election: Treas. Reg. §1.83-2(c) and Form 15620 both point to the IRS office where you file your federal return. Look up your Form 1040 paper filing campus, complete Form 15620 boxes 1–9 (or equivalent §1.83-2(e) language), write the Treasury / IRS / city / ZIP+4 block exactly, add a Section 83(b) attention line, and mail the signed original with USPS Certified Mail documentation. Expats should confirm whether Austin 73301-0215 applies before copying a domestic founder's envelope. Verify IRS.gov the week you mail—strategy articles are useless if the envelope goes to the wrong ZIP.
Primary sources
| Authority | Link |
|---|---|
| Treas. Reg. §1.83-2 | 26 CFR §1.83-2 |
| IRS Form 15620 (Apr 2025) | |
| IRS Where To File (domestic 1040) | IRS.gov |
| IRS Where To File (international 1040) | IRS.gov |
| IRC §7502 | 26 U.S.C. §7502 |
| IRC §7503 (weekends/holidays) | 26 U.S.C. §7503 |
Footnotes
Disclaimer: This article is educational only and is not tax, legal, or financial advice. Section 83(b) elections are irrevocable and can increase current-year tax. Confirm transfer dates, FMV, mailing addresses, and payment obligations with a qualified CPA, enrolled agent, or tax attorney before filing.
Footnotes
-
IRC §7502 and Treas. Reg. §301.7502-1 — timely mailing treated as timely filing under qualifying facts. ↩